

Blogs
The global bar loader market is projected to grow from USD 845 Million in 2020 to USD 1,390 Million by 2035. This upward trajectory is attributed to increasing industrial automation, expansion in manufacturing sectors, and adoption of advanced bar loader technologies. Year-over-year growth remains steady due to consistent demand from automotive, aerospace, and medical device manufacturers. Investments in smart factory solutions and Industry 4.0 integration further accelerate revenue generation. The marked rise in 2025 is closely linked to post-pandemic industrial revitalization, with revenue gains sustained well into the next decade.
Read More - https://bussinessinsights.com/research-report/global-bar-loader
The automotive industry remains the largest consumer of bar loaders, accounting for over one-third of market share in 2025, driven by demand for precision engineering and automation in mass production. Aerospace and general manufacturing follow closely, reflecting the importance of efficient, repeatable machining in these sectors. The medical industry’s adoption is rising due to stringent precision requirements, while construction and other industries primarily employ bar loaders for specialized mechanical components. As advanced automation spreads, the application landscape of bar loaders is expected to further diversify across industry verticals.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-bar-loader
Frequently Asked Questions
Who are the key players in Global Bar Loader industry?
The leading players in the Global Bar Loader industry include LNS Group, FMB Maschinenbau, IEMCA (Bucci Industries), Edge Technologies, and Haas Automation Inc. These companies drive innovation, offer a comprehensive range of bar feeders/loaders, and have a strong presence globally with robust distribution and after-sales networks.
What is the Global Bar Loader growth?
The Global Bar Loader market has experienced steady growth, with a CAGR of around 4% in recent years, driven primarily by increased adoption in automotive and precision engineering sectors. For instance, IEMCA reported increased sales in Asia-Pacific in 2023, signaling expanding demand for automation solutions.
Which segment accounted for the largest Global Bar Loader share?
The automotive manufacturing application segment accounted for the largest share of the Global Bar Loader market. Bar loaders are widely used in the automotive sector for high-speed, efficient, and automated machining of components, supported by leading OEMs striving for improved productivity and reduced labor costs.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global mower conditioners market is projected to witness steady growth between 2020 and 2035. Revenue figures show a consistent upward trajectory spurred by technological advances, increased mechanization, and a growing customer base worldwide. Between 2025 and 2030, the adoption rate accelerates among medium and large-scale farming enterprises, driving notable jumps in annual revenue, which surpasses $2.6 billion by 2035. Emerging markets in Asia-Pacific and Latin America are expected to play pivotal roles in sustaining this growth, supported by favorable government policies and increasing awareness about the benefits of modern forage equipment.
Read More - https://bussinessinsights.com/research-report/global-mower-conditioners
The agriculture application segment secures the largest share in the mower conditioners market for 2025, representing the principal use case for these machines due to the need for efficient forage crop management. Landscaping follows, reflecting growing urbanization and demand for professionally maintained green spaces across cities. Sports and recreation also register notable share, driven by investments in high-quality turf for golf courses and parks. These trends are buoyed by governments and commercial clients prioritizing sustainability and aesthetic upgrades, spurring increased adoption across non-agricultural sectors. Vendors are responding by diversifying their offerings to meet specialized requirements in each segment, further fueling market expansion.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-mower-conditioners
Frequently Asked Questions
Who are the key players in Global Mower Conditioners industry?
The key players in the Global Mower Conditioners industry include John Deere, AGCO Corporation, Kuhn Group, Kubota Corporation, and New Holland (CNH Industrial). These companies excel in producing innovative agricultural machinery, offer robust dealer networks, and continuously invest in R&D to enhance performance, reliability, and efficiency in mower conditioners.
What is the Global Mower Conditioners growth?
The Global Mower Conditioners market is witnessing steady growth, driven by rising demand for efficient forage processing. Recent product launches, such as John Deere’s 2023 expanded model lineup, and technological advancements in automation and precision farming equipment, are fueling adoption in developed and emerging markets alike.
Which segment accounted for the largest Global Mower Conditioners share?
The largest share of the Global Mower Conditioners market is held by agriculture and forage applications. These applications require reliable and high-efficiency grass cutting and conditioning for optimal silage and hay production, prompting farmers to invest significantly in advanced mower conditioners.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Airborne Wind Energy Equipment Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The global market revenue for Airborne Wind Energy Equipment is forecast to grow steadily from USD 670 Million in 2020, reaching USD 1,250 Million in 2025 and accelerating to USD 6,430 Million by 2035. This rapid surge is fueled by heightened governmental targets for renewables, robust R&D funding, and a diversification of application sectors. Between 2025 and 2035, the sector is set to witness one of the highest CAGRs in the alternative energy industry.
Read More - https://bussinessinsights.com/research-report/global-airborne-wind-energy-equipment
Onshore applications remain dominant in 2025, claiming 41% of the market share as businesses and communities prioritize cost-effective, reliable wind solutions. Offshore installations, leveraging high-wind environments, contribute 26% to the total market, spearheaded by projects from companies like Ampyx Power. Remote power applications, including island and temporary installations, hold 15%, while military & defense and emergency response together make up 13%. This reflects an expanding use-case spectrum and growing relevance in energy transition strategies.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-airborne-wind-energy-equipment
Frequently Asked Questions
Who are the key players in Global Airborne Wind Energy Equipment industry?
Key players include Ampyx Power, Kitepower, SkySails Power, Makani (formerly backed by Google), and Altaeros. These companies innovate with airborne wind turbines, kites, and tethered systems, focusing on renewable energy generation using high-altitude winds to provide sustainable and cost-effective electricity.
What is the Global Airborne Wind Energy Equipment growth?
The Global Airborne Wind Energy Equipment market is experiencing rapid growth, largely driven by increasing investments and successful demonstration projects. For example, SkySails Power reported significant commercial expansion in 2023, highlighting rising adoption and the sector’s move toward commercialization and scalability.
Which segment accounted for the largest Global Airborne Wind Energy Equipment share?
Power generation applications lead the market share, as airborne wind energy systems are primarily used for generating electricity in remote areas or where conventional wind turbines are impractical. Increased focus on renewable energy transition has made this segment dominant, especially for off-grid and rural electrification projects.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global mobile blender market has shown robust growth from 2020 and is projected to continue expanding at a notable CAGR through 2035. Revenue was valued at USD 780 Million in 2021, reached USD 950 Million in 2025, and is forecast to surpass USD 2,600 Million by 2035. Key drivers include technological innovation, shifting consumer preferences towards portable appliances, and increasing investment from both global and regional players. The market’s momentum is reinforced by new product launches and expanded distribution channels, sustaining interest and repeat purchases among consumers worldwide.
Read More - https://bussinessinsights.com/research-report/global-mobile-blender
Personal use remains the dominant application in the mobile blender market for 2025, accounting for nearly half the overall share. The surge is propelled by growing health and fitness awareness and the need for rapid, nutritious food preparation at home and on-the-go. Commercial, travel, and sports-centric applications collectively constitute a significant market share, reflecting demand in offices, gyms, and travel scenarios. Outdoor and specialty uses are also gaining relevance as brands introduce rugged and high-efficiency models targeting travelers and adventure enthusiasts. Brands are responding to these dynamics by offering tailored product lines for each major application.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-mobile-blender
Frequently Asked Questions
Who are the key players in Global Mobile Blender industry?
The top 5 players in the Global Mobile Blender industry are NutriBullet, BlendJet, PopBabies, Hamilton Beach, and Cuisinart. These companies offer innovative portable blender solutions, focusing on battery life, blending efficiency, and sleek design. Their extensive distribution channels and robust marketing strategies solidify their leading positions in the market.
What is the Global Mobile Blender growth?
The Global Mobile Blender market has experienced significant growth, particularly after 2022, driven by rising health consciousness and increasing adoption of on-the-go kitchen appliances. BlendJet, for instance, reported a surge in sales due to its powerful marketing campaigns and partnerships with fitness brands.
Which segment accounted for the largest Global Mobile Blender share?
The largest share of the Global Mobile Blender market comes from the household application segment. The growing trend for kitchen convenience, meal prepping, and health-focused lifestyles among consumers has significantly fueled demand, with products tailored for quick smoothies and protein shakes at home seeing the highest adoption rates.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global Food Contract Manufacturing Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The global food contract manufacturing market is projected to grow steadily from 2020 to 2035, with revenue rising from USD 48,000 Million in 2020 to an estimated USD 128,500 Million by 2035. The market recorded robust momentum during 2021-2025, driven by shifting consumer preferences, technology advancement, and regional expansion. Strong CAGR performance is seen during 2025-2030 due to scalable outsourcing opportunities and retailer emphasis on private label offerings. The forecast period up to 2035 further reflects sustained industry investment and adoption of hybrid retail and distribution channels, making contract manufacturing an increasingly integral part of the global food ecosystem.
Read More - https://bussinessinsights.com/research-report/global-food-contract-manufacturing
The retail segment commands the largest share of the global food contract manufacturing market by application in 2025, at 37%. Food service applications, encompassing quick-service restaurants and catering, comprise 24% due to heightened demand for outsourced meal preparation. Industrial uses, featuring bulk ingredients and intermediates for other manufacturers, account for 18%. Institutional applications, including healthcare and education, contribute 11%, as organizations optimize foodservice costs. Online platforms are gaining popularity, representing 7% of the market, driven by the surge in e-commerce grocery services. Other applications, such as specialty and niche food production, collectively make up 3%, underlining a diversified application landscape catering to varying end-user needs.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-food-contract-manufacturing
Frequently Asked Questions
Who are the key players in Global Food Contract Manufacturing industry?
The top five players in the global food contract manufacturing industry are Buhler Group, Tetra Pak International S.A., Nestlé, Cargill, and Nissin Foods Holdings. These companies lead due to their extensive manufacturing capabilities, global supply chains, innovation in food processing technologies, and strong partnerships with established food brands.
What is the Global Food Contract Manufacturing growth?
The global food contract manufacturing market has seen significant growth, with recent reports indicating a CAGR of over 9% between 2021 and 2024. Companies like Tetra Pak have reported increased demand for outsourced food processing due to shifting consumer preferences and cost-effective production models.
Which segment accounted for the largest Global Food Contract Manufacturing share?
The beverages segment accounted for the largest share in global food contract manufacturing. This is driven by the rising consumption of ready-to-drink products and the demand for specialized bottling and packaging solutions, with numerous manufacturers focusing on outsourcing beverage production to optimize efficiency and quality.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Global General Purpose Lighting Equipment Market Size, Share & Forecast Report, 2034
By Manisha , 2026-09-16
The global general purpose lighting equipment market is projected to climb from $82,400 Million in 2025 to $140,800 Million by 2035, reflecting a robust CAGR driven by widespread adoption of energy-efficient and smart lighting solutions. Revenue growth is underpinned by investments in urban development, infrastructure upgrades, and heightened demand for integrated lighting systems. North America and Asia-Pacific remain primary revenue contributors, spurred by rapid urbanization and government initiatives on sustainability. Significant growth potential is also emerging from Latin America, the Middle East, and Africa as they accelerate city modernization programs.
Read More - https://bussinessinsights.com/research-report/global-general-purpose-lighting-equipment
The global market share by applications in 2025 shows residential lighting leading the segment, driven by renovation activities, urban population growth, and smart home adoption. Commercial and industrial applications collectively account for over half the market demand, propelled by large-scale facility upgrades, sustainability initiatives, and regulatory compliance. Outdoor and automotive applications also witness continual growth as governments invest in smart city and public infrastructure projects, including street lighting and smart parking solutions. The increasing integration of adaptive and connected lighting in commercial spaces is bolstering growth in hospitality, retail, and office environments.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-general-purpose-lighting-equipment
Frequently Asked Questions
Who are the key players in Global General Purpose Lighting Equipment industry?
Key players include Signify (Philips Lighting), Osram Licht AG, GE Lighting (a Savant company), Acuity Brands, and Eaton Corporation. These companies are recognized for their innovation, extensive product portfolios, global reach, and continuous investment in energy-efficient lighting technologies, catering to diverse residential, commercial, and industrial sectors.
What is the Global General Purpose Lighting Equipment growth?
The Global General Purpose Lighting Equipment market has witnessed steady growth, driven by increasing demand for energy-efficient solutions. For example, Signify reported strong year-on-year revenue growth in its LED segment in 2023, citing accelerated adoption of intelligent lighting systems in both developed and emerging markets.
Which segment accounted for the largest Global General Purpose Lighting Equipment share?
The residential application segment commands the largest market share in the Global General Purpose Lighting Equipment market. The rise in urbanization, increasing home renovation projects, and consumer demand for smart, energy-saving lighting solutions are significant contributors to this dominance within the application landscape.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Commercial Payment Cards Market to Hit $364.76B by 2032, Growing at 6.98% CAGR
By PW Consulting, 2026-09-16
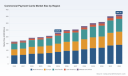
Navigating the Next Wave: Strategic Insights from the Commercial Payment Cards Market Research 2026
The landscape of corporate spending is undergoing a seismic shift. As businesses grapple with inflationary pressures, evolving regulatory frameworks, and the demand for seamless digital integration, the commercial payment card sector has emerged as a critical lever for operational efficiency. For decision-makers navigating the fiscal calendar of 2026, understanding the trajectory of this market is not merely an academic exercise—it is a strategic imperative. PW Consulting is proud to unveil our latest comprehensive market research, designed to equip leaders with the intelligence needed to capitalize on growth opportunities and mitigate emerging risks in the commercial payment ecosystem.
This research is anchored in rigorous data analysis covering historical performance from 2020 through 2025 and extending robust forecasts through 2032. The macro-environment presents a compelling story of resilience and expansion. In 2025, the global revenue for commercial payment cards reached approximately 229.05 billion USD. Looking ahead, the market is projected to climb to 249.66 billion USD in 2026, marking a significant inflection point in corporate adoption rates. Our forecast models indicate a steady compound annual growth rate of 6.98 percent throughout the forecast period, with revenues expected to surpass 364.76 billion USD by 2032. These figures underscore a sustained appetite for flexible payment instruments that bridge the gap between traditional corporate treasury functions and modern procurement needs.
Decoding Market Concentration and Competitive Forces
One of the most critical aspects of our analysis focuses on the competitive dynamics that define the industry. The market is characterized by a moderate level of concentration, where strategic positioning among top-tier players dictates the pace of innovation. Our report details a landscape where the top three companies command a combined market share of roughly 49.5 percent, while the top five entities control approximately 62.8 percent of the revenue pool. This structure suggests that while dominant networks hold significant sway, there remains substantial room for specialized issuers and niche providers to carve out profitable segments.
Plastic Cards Market
The competitive arena is populated by a diverse mix of global network operators and specialized issuers. Giants like American Express, Visa, and Mastercard continue to dominate the infrastructure layer, offering robust networks that support virtual purchase cards and corporate spend management solutions. American Express, headquartered in New York, remains a key player in issuing commercial payment cards including virtual purchase cards for business-to-business procurement. Similarly, Visa, based in San Francisco, operates a global network supporting commercial payment cards including virtual cards for corporate spend management, while Mastercard, located in Purchase, NY, provides network infrastructure with a focus on virtual and single-use variants for B2B transactions.
However, the ecosystem extends far beyond these primary networks. Discover Financial Services, based in Riverwoods, IL, issues commercial payment cards for business expense tracking and virtual solutions, catering to specific expense management needs. International reach is exemplified by JCB in Tokyo and UnionPay in Beijing, the latter facilitating commercial payment cards with contactless and virtual options to support cross-border commerce. On the specialized issuer front, companies like WEX in Minneapolis provide commercial fleet and virtual payment cards for business expenses, whereas Corpay in Nashville issues and manages commercial payment cards for corporate travel and expense programs.
Innovation is also being driven by agile entrants and standards bodies. Engine, based in Denver, recently made waves with the launch of the Engine X Visa-branded corporate charge card specifically for small and mid-sized businesses. This product features spending controls and travel rewards, directly addressing the needs of the SMB segment which often feels overlooked by larger issuers. Furthermore, standards development plays a crucial role in interoperability and security. X9, the standards body in Annapolis, MD, developed and published X9.149 for single-use virtual business-to-business payment cards, aiming to streamline transaction efficiency.
Recent Developments Shaping the 2026 Landscape
Real-time intelligence is vital in a sector moving this fast. Our research integrates the latest developments that are actively reshaping the value proposition for corporate clients. In March 2026, Engine announced the launch of their corporate charge card, featuring spending limits, merchant restrictions, and up to 10 percent rewards on business travel. This move highlights a trend toward incentivizing specific spending categories while maintaining strict control parameters, a balance that many finance teams are seeking.
Simultaneously, the regulatory and standards environment is tightening to support higher efficiency and security. In April 2026, the Accredited Standards Committee X9 published the X9.149 standard for single-use virtual purchase card payment automation. This development is designed to improve B2B transaction efficiency and reconciliation following ISO 20022 messaging standards. Such standardization efforts are critical for reducing friction in accounts payable processes and enhancing the auditability of corporate spending.
Beyond specific product launches, broader industry dynamics are influencing market behavior. The Federal Reserve Board reported on average debit card interchange fees by payment card network in December 2025, providing essential data for cost-benefit analyses of different card programs. Security remains paramount, with the PCI DSS Card Production and Provisioning Physical and Logical Security Requirements defining standards for card manufacturing, transport, and personalization. Additionally, the Payment Card Industry Data Security Standard version 4.0 guides organizations on card data handling and compliance, a critical consideration for any firm integrating payment cards into their IT infrastructure.
Infrastructure costs also play a background role in the economics of payment processing. The American Society of Civil Engineers 2025 Infrastructure Report Card noted that deployment costs for broadband infrastructure increased over 10 percent with materials and labor as primary drivers. While this relates to physical infrastructure, it impacts the broader digital ecosystem supporting payment technologies. Furthermore, macro-level shifts are occurring, as highlighted by the McKinsey Global Payments Report in September 2025, which pointed to growing payment sovereignty initiatives in regions such as Europe and Brazil to reduce reliance on global intermediaries. This trend could influence network selection and localization strategies for multinational corporations.
Segmentation Dynamics and Application Scenarios
Understanding where the revenue is generated is key to allocating resources effectively. Our research delves deep into the segmentation of the market by type and application, revealing distinct growth drivers within each category. The market is segmented by type into Credit Cards, Debit Cards, and Prepaid Cards. Credit cards continue to hold a substantial portion of the market value, reflecting their utility in managing cash flow and earning rewards, while Debit Cards offer a controlled spending mechanism linked directly to funds. Prepaid Cards also represent a significant segment, often utilized for specific budgeting purposes or employee allowances.
From an application perspective, the divide between Large Business Cards and Small Business Cards illustrates the diverse needs across the corporate spectrum. Large Business Cards constitute a major share of the application market, driven by high-volume procurement and complex travel requirements. Small Business Cards, while representing a smaller total revenue share compared to the enterprise segment, are witnessing heightened innovation and competitive pressure from issuers like Engine looking to capture the SME market. Our report provides granular analysis of how these segments interact with regional dynamics and type preferences without exposing the specific numerical splits that constitute our core proprietary intelligence.
Geographic distribution also plays a pivotal role in strategy formulation. The market serves key regions including North America, Europe, Asia Pacific, Latin America, and Mideast and Africa. Each region presents unique regulatory environments, adoption rates, and competitive intensities. For instance, payment sovereignty trends may impact strategies in Europe and Latin America differently than in North America. Our analysis contextualizes these regional variations to help clients prioritize market entry or expansion efforts based on their specific risk tolerance and growth objectives.
The Strategic Value of Comprehensive Intelligence
Why does this level of detail matter for your 2026 planning? In a market projected to grow by over 130 billion USD between 2026 and 2032, the margin for error shrinks as competition intensifies. Access to detailed segmentation data, competitive profiling, and regulatory roadmaps allows organizations to move from reactive spending management to proactive financial strategy. Whether you are a issuer looking to refine your product portfolio, a corporate treasurer optimizing expense policies, or an investor assessing the viability of fintech ventures in the payments space, this report provides the foundational knowledge required to make informed decisions.
The report goes beyond high-level numbers to explore the operational realities faced by market participants. It examines how reimbursement dynamics, influenced by factors such as interchange fee structures, affect the total cost of ownership for corporate card programs. It also assesses how compliance with evolving security standards impacts procurement timelines and vendor selection. By synthesizing data on market concentration, company profiles, and recent developments, we offer a 360-degree view of the ecosystem.
Our analysis of key companies includes detailed profiles covering their headquarters, operational focus, and strategic moves. For example, understanding the focus of WEX on fleet and virtual payment cards versus Corpay's emphasis on corporate travel and expense programs helps tailor partnership or benchmarking strategies. Similarly, tracking the standardization efforts of bodies like X9 ensures that technology investments align with future-proof protocols.
Commercial Payment Cards Market
Unlock the Full Intelligence
The insights summarized here represent only the surface of the comprehensive intelligence available in the full PW Consulting Commercial Payment Cards Market Research. To truly leverage the 6.98 percent CAGR opportunity and navigate the complexities of a market reaching 364.76 billion USD by 2032, decision-makers need access to the complete dataset, detailed forecasts, and proprietary analytical models.
We invite you to access the source webpage to download the full report. There you will find the specific regional growth rates, detailed application segment valuations, and deep-dive competitive benchmarking that cannot be fully disclosed in this overview. Equip your team with the precise data needed to outperform in the evolving commercial payment landscape. Visit our report page today to secure your copy and start transforming market intelligence into strategic advantage.
For detailed analysis of this topic, please visit the official page: Commercial Payment Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Market revenue for indoor air quality monitors in China demonstrates robust growth, rising from USD 520 Million in 2020 to an anticipated USD 2,120 Million in 2035. Key growth inflections are observed post-2025, attributed to technological advancements, policy boosts, and increased user awareness. This upward trajectory reflects both expanded consumer base penetration and upgrades within commercial and government facilities, indicating sustained value creation for stakeholders in the coming decade.
Read More - https://bussinessinsights.com/research-report/china-indoor-air-quality-monitor-market
The residential sector leads the indoor air quality monitor market in China for 2025, reflecting the increased consumer priority on health and safety within homes. The commercial segment, encompassing offices, malls, and retail, follows closely as businesses aim to create healthier workspaces and meet regulatory requirements. Industrial and institutional usage is rising in line with stricter occupational health standards and corporate sustainability initiatives. This segmentation underlines the diversified deployment of IAQ monitors beyond just residential use, signaling market maturity and wider acceptance amid different end-users.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-indoor-air-quality-monitor-market
Frequently Asked Questions
Who are the key players in China Indoor Air Quality Monitor Market industry?
The top five players in the China indoor air quality monitor market include Thermo Fisher Scientific, Siemens AG, Honeywell International, Aeroqual, and Qingdao Tianer. These companies are recognized for their advanced technologies, strong distribution networks, innovative product ranges, and commitment to research and development in environmental monitoring solutions.
What is the China Indoor Air Quality Monitor Market growth?
The China indoor air quality monitor market has experienced robust growth in recent years, driven by increasing public health awareness and strict government regulations. For instance, in 2023, Honeywell reported increased demand for its smart air quality monitoring devices amid rising urbanization and concerns over particulate pollution.
Which segment accounted for the largest China Indoor Air Quality Monitor Market share?
The commercial segment held the largest market share in the China indoor air quality monitor market. Offices, shopping malls, schools, and hospitals are increasingly adopting air quality monitoring systems to ensure healthy indoor environments and compliance with government standards, thus driving significant demand in this application area.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The global mobile antivirus market is poised for robust revenue growth, projected from $5,800 Million in 2020 up to $21,550 Million by 2035. The compounded growth rate is fueled by increased cyber risks, enterprise digitization, and expansion into underserved markets. Post-pandemic digital adoption and regulatory compliance particularly contributed to steep rises between 2023-2025, with the forecast period showing steady gains as advanced technologies become mainstream and user awareness deepens.
Read More - https://bussinessinsights.com/research-report/global-mobile-antivirus
In 2025, Android maintains dominance in the mobile antivirus application market, largely due to its vast global user base and the higher frequency of malware attacks targeting the platform. iOS appeals to users seeking robust but lightweight protection, given iOS’s built-in security but rising phishing threats. Other platforms, including Windows, Blackberry, and Symbian, have a much smaller share as their presence in the global handset market declines. Security vendors continue to focus R&D on Android while enhancing cross-platform compatibility.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-mobile-antivirus
Frequently Asked Questions
Who are the key players in Global Mobile Antivirus industry?
The top 5 players in the Global Mobile Antivirus industry are Avast, McAfee, Kaspersky Lab, NortonLifeLock (Norton), and Bitdefender. These companies provide comprehensive mobile security solutions, including malware detection, real-time protection, and privacy features, both for Android and iOS devices. Their global reach ensures robust competitive influence.
What is the Global Mobile Antivirus growth?
The Global Mobile Antivirus market has witnessed significant growth, with a CAGR exceeding 10% in recent years. Companies like Avast reported increased adoption due to rising mobile threats and increased smartphone usage. Market expansion is fueled by enterprise mobility trends and heightened consumer awareness about mobile cybersecurity.
Which segment accounted for the largest Global Mobile Antivirus share?
The consumer application segment accounted for the largest share in the Global Mobile Antivirus market. Due to a surge in mobile device usage and the rising threat of personal data theft, end-users are increasingly installing antivirus apps for personal protection, driving higher adoption rates in this application area.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The market has experienced exponential revenue growth from 2020 to 2025, with total revenue rising from $850 million in 2020 to $2,430 million in 2025. Future revenue is projected to reach $13,400 million by 2035, marking a compound annual growth rate exceeding 19% over the period. This trajectory is fueled by significant advancements in SiC device manufacturing, widespread EV adoption, and the accelerating deployment of renewable energy worldwide.
Read More - https://bussinessinsights.com/research-report/global-sic-inverter
Electric vehicles represent the leading application for SiC inverters in 2025, making up 38% of market share as automakers scale production of EVs globally. Renewable energy systems, including solar and wind, account for 27%, fueled by aggressive renewable installation targets. Industrial motor drives comprise 15%, reflecting ongoing automation and electrification trends, followed by rail traction at 9%, power supplies 7%, and other applications at 4%. The increasing emphasis on energy efficiency and emission reductions in mobility and energy sectors continues to drive robust demand.
Request Free Sample - https://bussinessinsights.com/request/machinery-and-equipments/global-sic-inverter
Frequently Asked Questions
Who are the key players in Global SiC Inverter industry?
The top 5 players in the Global SiC Inverter industry are Infineon Technologies, Mitsubishi Electric, ON Semiconductor, Fuji Electric, and ROHM Semiconductor. These companies are recognized for their advanced SiC technology, wide portfolio of inverter products, and strong market presence across automotive, industrial, and renewable energy applications.
What is the Global SiC Inverter growth?
The Global SiC Inverter market is experiencing rapid growth, driven by rising electric vehicle adoption and renewable energy initiatives. For example, Infineon Technologies reported significant growth in SiC inverter sales in 2023, attributing it to increased EV production and the shift towards more efficient power electronics.
Which segment accounted for the largest Global SiC Inverter share?
The automotive segment accounted for the largest share of the Global SiC Inverter market. The demand for high-efficiency inverters in electric vehicles, especially for traction inverters, has surged as automakers like Tesla and BYD integrate SiC-based solutions to enhance performance and range.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com